Explore effective strategies for personalizing your retirement plan to better enhance your income and liquid savings as you prepare for retirement.
Retirement planning is evolving as life expectancies increase, Social Security faces challenges, and long-term care expenses continue to rise. It's no longer enough to rely purely on traditional savings vehicles like 401(k)s and IRAs. Home equity is also a significant asset that can factor into your retirement strategy. Rather than adhering to generic guidelines, it's vital to tailor your retirement plan to fit your specific needs and circumstances.
Establishing Your Base Plan
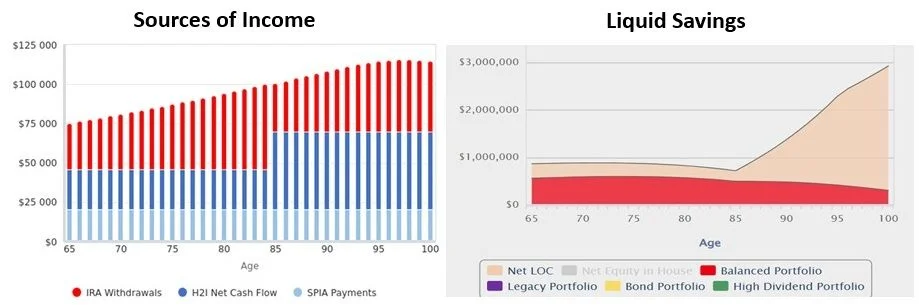
The concept of a "base plan" is central here. The IRA4Income strategy, which I previously outlined in articles discussing long-term care solutions and income increases, underscores the importance of creating a personalized financial framework. This approach is designed to deliver a higher income while ensuring access to liquid assets when needed.
To achieve a solid understanding of this strategy, consider integrating these core components:
- An IRA invested with a balanced allocation of 50% in fixed income and 50% in stocks.
- Lifetime income options like immediate annuities that can be set to start right away or deferred through a Qualified Longevity Annuity Contract (QLAC).
- A Home Equity Conversion Mortgage (HECM) that can provide both income and liquidity.
These items may not be revolutionary, but when combined effectively through the IRA4Income framework, they contribute to a robust financial foundation. The plan is constructed based on various economic assumptions that include investment return rates, personal income growth expectations, and current interest rates from annuity and HECM offerings.
Assessing Retirement Income and Savings
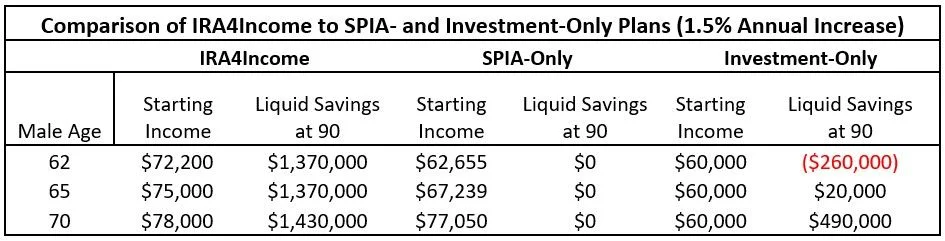
When juxtaposing the IRA4Income approach with two traditional retirement income strategies—a single premium income annuity (SPIA) providing guaranteed income without liquidity and an investment-only plan devoid of guaranteed annuity income—one can appreciate the unique advantages of this method. The IRA4Income plan balances high initial income with the liquidity needed later in retirement, which is particularly beneficial when healthcare costs often surge during those later years.
The Importance of Personalization
Why is personalizing your retirement plan essential? A solid base IRA4Income framework delivers impressive outcomes, particularly in generating starting income and ensuring liquid savings into your 90s. The results indicate how different modifications can optimize these two critical aspects. Once you have established a basic plan, a qualified adviser can help you tailor it to your specific goals and lifestyle aspirations rather than merely suggesting reductions in spending.
Strategies for Customizing Your Plan
Here are several ways to personalize your retirement strategy:
Enhancing Income Potential
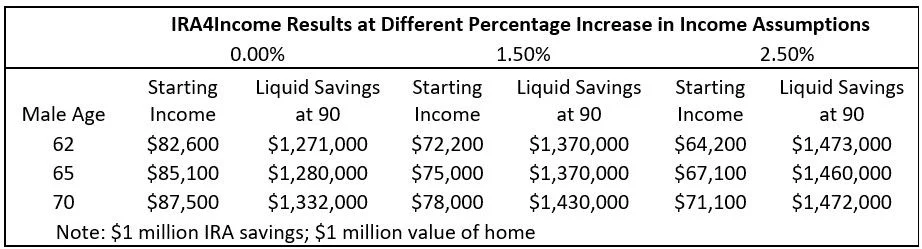
Consider adjusting your income assumptions. For instance, varying the rate of inflation protection can significantly affect your long-term income projections. By recalibrating these parameters, you can better align your retirement income with future cost-of-living increases.
Managing Investment Risk
Do you prefer a higher or lower risk exposure? Adjusting the assumptions of expected returns can create a safer or more aggressive retirement strategy. A higher return assumption, for example, may increase initial income but could also expose you to market volatility.
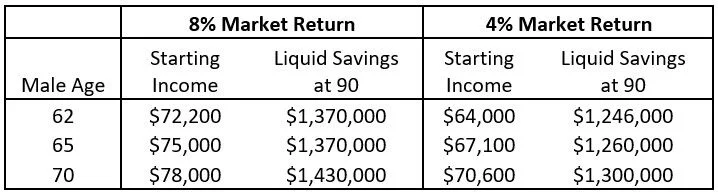
Creating a Legacy
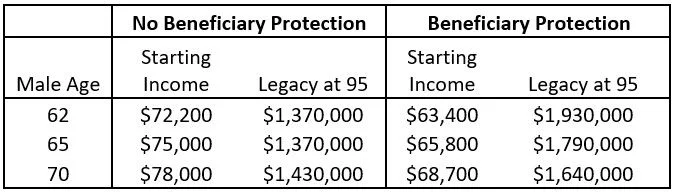
For those focusing on legacy planning, incorporating annuities into your strategy can ensure that beneficiaries are accounted for—a crucial aspect that could provide peace of mind as you age.
Tax Efficiency
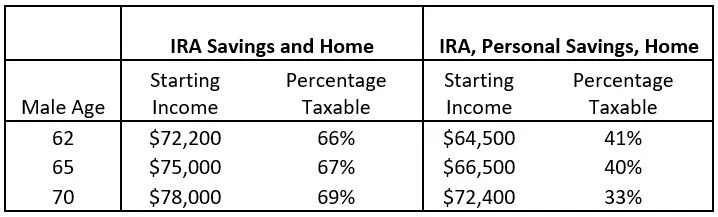
Lastly, addressing tax implications is key. Many retirees rely solely on tax-deferred accounts such as IRAs for retirement income, which can lead to substantial tax burdens. Diversifying income sources can minimize this strain. For instance, leveraging a HECM line of credit can offer tax-free income, allowing you to manage your tax liabilities more effectively.
Conclusion: Craft Your Retirement Future
The IRA4Income strategy showcases how combining traditional retirement savings with home equity can enhance both income and liquidity. Not only does this approach have the potential to boost retirement income by 50% to 75%, but it also allows for comprehensive stress-testing against future long-term care needs or other financial events.
To embark on this journey of personalized retirement planning, consider taking the first step by ordering an IRA4Income base plan, setting the foundation for a retirement strategy that aligns with your unique goals.
Related Content
- What the HECM? Combine It With a QLAC and See What Happens
- Transform Your Retirement Plan With This Powerful Combo
- How Combining Your Home Equity and IRA Can Supercharge Your Retirement
- Is Your Retirement Solution Hiding in Plain Sight?
- How Your Home Can Fill Gaps in Your Retirement Plan
This article presents the views of the contributing adviser and does not reflect the Kiplinger editorial staff. You can review adviser records through the SEC or FINRA.


