Choosing a pension survivorship option has significant implications for your financial future. Exploring alternatives like life insurance can provide better outcomes for both you and your spouse.
One of the primary concerns many people have is ensuring their spouse remains financially secure if they pass away. When it comes to pension distribution options, picking the right choice at retirement is essential, as it significantly impacts both current income and long-term coverage for your partner.
A common instinct is to opt for the survivor option, which offers a continuous income stream for your spouse after your death. However, it’s critical to consider that accepting this option generally means a reduction in your own pension payout while you're alive.
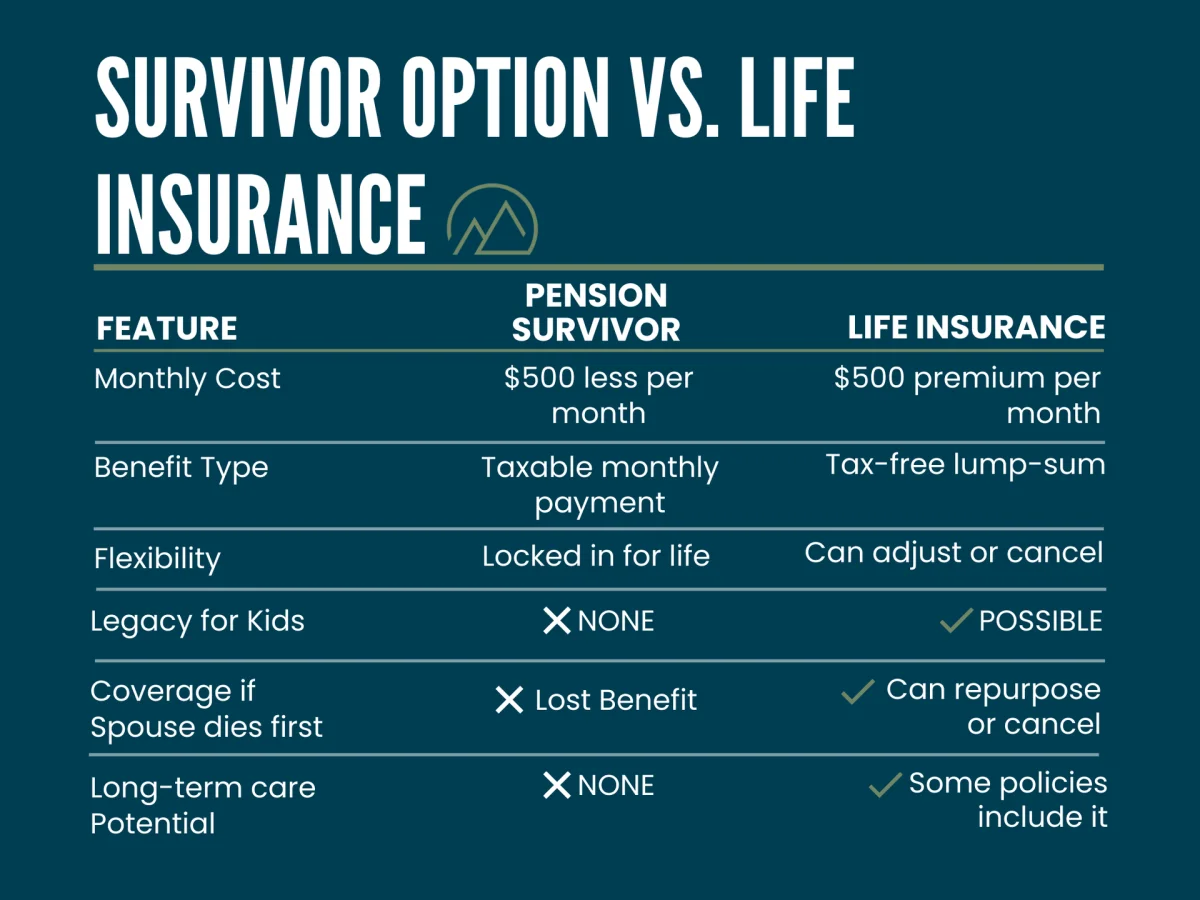
For instance, at Peak Retirement Planning, I encountered a client with a pension plan that provided $5,000 monthly payments for their lifetime. Upon selecting the survivor option—which guaranteed their spouse 50% of the pension after their passing—they faced a 10% reduction in their monthly benefit, receiving $4,500 instead. Subsequently, their spouse would receive $2,500 per month.
The question then arises: Is this 10% reduction worth the peace of mind such a decision brings? It’s crucial to dissect this financial choice further, especially when considering alternatives. An extra $500 monthly can significantly affect your overall retirement experience.
Exploring Alternative Coverage: Life Insurance
Many clients explore the option of replacing the pension survivor benefit with life insurance. For around $500 a month, individuals aged 60 in average health might secure a permanent life insurance policy with a death benefit of approximately $350,000. This ensures that should the policyholder pass away, their spouse would receive that amount without any additional payment required, fostering a more substantial safety net at death.
If a term life insurance policy is preferred, one could achieve a death benefit closer to $1 million for a 20-year period, thereby ensuring robust coverage for a specified timeframe. Blending both policies often creates a more comprehensive solution that could provide income stability to your spouse upon your demise.
The life insurance payout carries additional advantages over a pension. Primarily, the death benefits are typically tax-free, whereas pension payments are taxable. This tax imposition could be even higher for surviving spouses due to what's known as the "widow’s penalty," where a surviving spouse often faces higher tax rates as a single filer.
Moreover, should your spouse pass away first, the life insurance benefit could be transferred tax-free to your children, further extending its financial utility. Certain life insurance products even allow for a long-term care provision, letting you access benefits in case you require additional care later in life. Furthermore, permanent life insurance policies may build cash value that you can utilize, providing an adaptable financial resource as needed.
However, it's essential to note that insurability plays a crucial role. Individuals need to be in acceptable health to secure life insurance benefits, and costs will fluctuate based on personal health metrics. Consulting with a financial planner experienced in comprehensive retirement planning, including pension analysis and life insurance, can facilitate a more informed decision-making process.
Assessing the Viability of Your Pension
Another reason to consider alternate strategies beyond the survivor option is the long-term stability of your pension itself. Increasing longevity among the populace paired with fewer contributors has put considerable stress on many pension plans, leading to concerns about their sustainability going forward. Many pensions report being underfunded, raising alarms regarding their reliability as a long-term financial resource.
Choosing not to pursue the pension survivor option could provide greater control over your retirement income and long-term financial planning. If your spouse is significantly younger or expected to live longer than you, it may make sense to forgo a plan that you might not benefit from fully.
Nevertheless, if you determine that neither a capable life insurance policy nor sufficient investments to cover potential expenses are available, it might be prudent to stick with the pension survivor option. The risk of leaving your spouse without sufficient financial support in case of your early passing can often outweigh any perceived benefits of maximizing your pension payouts.
It’s imperative to have a clear plan for your partner’s financial needs if you choose not to take the survivor benefit. Ensure you explore potential life insurance policies or other forms of savings and investments to guarantee they aren’t left vulnerable.
Consider Seeking Expert Guidance
In summary, deliberating which pension option to select is significant and can greatly influence your financial peace of mind during retirement. Collaboration with a specialized financial planner can yield insights tailored to your unique situation, helping determine whether the survivor benefit, life insurance, or another strategy better serves both your needs and those of your spouse.
As you navigate this important phase, consider your spouse’s financial future, your current retirement needs, and the long-term viability of your financial plans.


