Federal leaders are promoting CHOICE Arrangements in Texas, a flexible health benefit model that empowers employees to choose their coverage based on individual needs.
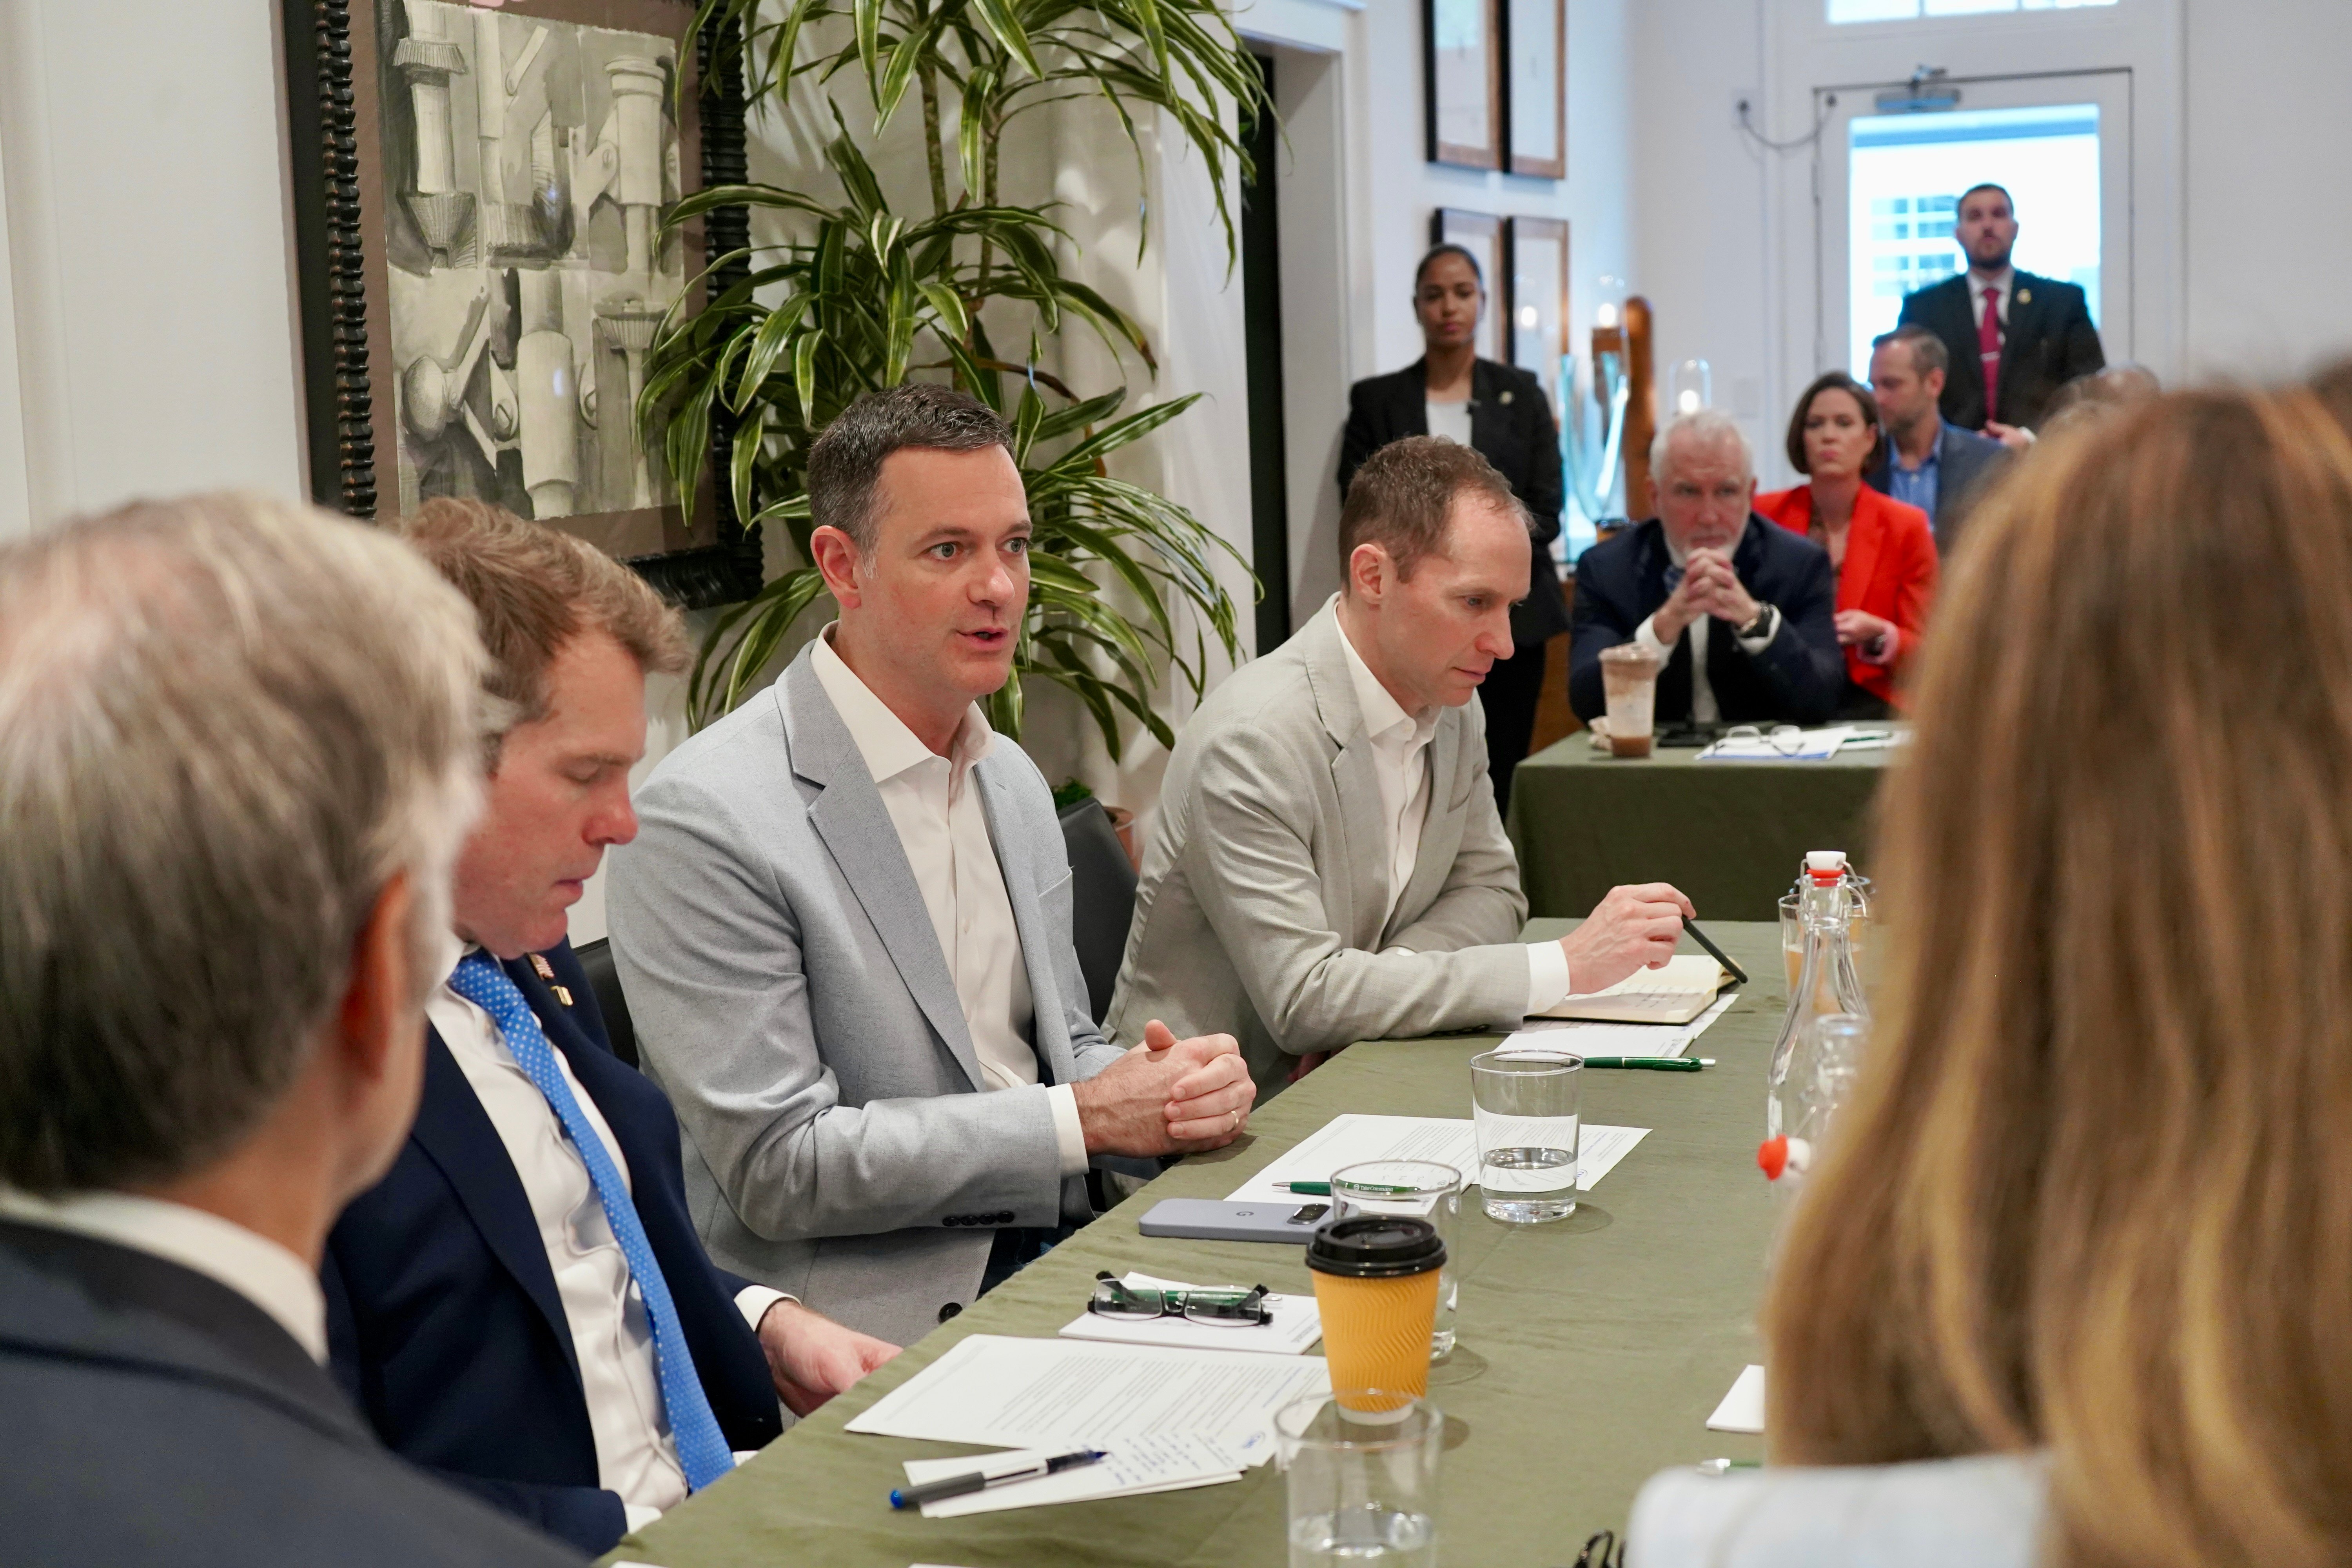
Federal leaders have recently shifted focus towards an employer health-benefit model that many businesses are still unfamiliar with. On September 30, Take Command hosted the event CHOICE in Action: Texas, featuring representatives from the Centers for Medicare & Medicaid Services (CMS), the U.S. Small Business Administration (SBA), and local Texas employers.
The discussion revolved around CHOICE Arrangements, the public-facing name for Individual Coverage Health Reimbursement Arrangements (ICHRAs). However, this event was more significant than just a rebranding; it highlighted a growing recognition of flexible health benefits in the workplace.
CMS and SBA are keen on increasing awareness regarding this model and guiding employers on how to evaluate and implement it effectively. For employers wrestling with difficult renewals, attempting to offer benefits for the first time, or catering to a workforce with diverse coverage needs, the increased attention is a crucial reason to explore this model further.
Amanda Crawford, Texas Department of Insurance Commissioner, also participated, bringing valuable state-level insight to this important conversation about Texas employers’ needs.
Understanding CHOICE Arrangements
A CHOICE Arrangement is a health benefit funded by employers. Instead of providing a traditional group health plan for employees, employers supply tax-free funds that eligible employees can use to purchase their qualifying individual health insurance. This allows employees to select coverage that best suits their preferences, including considerations of monthly premiums, deductibles, and provider networks.
The significant change lies not in the funding but in the decision-making process regarding health plans. A key point made during the Texas conversation was the clarification that while the employer supplies the funds, employees have the autonomy to choose their coverage. Employees must enroll in qualifying coverage and adhere to the arrangement’s stipulations to receive reimbursements—a fact that was underlined when the Austin American Statesman raised questions about the perception of employer-provided benefits.
Why the Focus on CHOICE?
CMS and SBA are promoting CHOICE Arrangements as a flexible solution for businesses providing health benefits. For new employers entering this landscape, this model offers a defined contribution approach without the obligation of selecting one group plan for the entire workforce. Existing employers facing issues with participation, cost increases, or varied employee needs can also benefit from this model.
Employees gain more control over their health insurance, allowing them to select individual plans that match their specific requirements rather than relying on a one-size-fits-all group plan. However, this attention should not be interpreted as a blanket recommendation for every employer to switch—rather, it indicates that more employers will be introduced to this concept and will need a clear understanding of its suitability for their situation.
As CMS Administrator Dr. Mehmet Oz articulated to the attendees, “We’re not telling you to do it, but we’re telling you, you need to look into it.” This illustrates the need for careful evaluation against current expenses, employee demographics, location, and administrative considerations before making a switch.
Key Factors for Employers to Consider
Participants in the Texas event underscored several scenarios that might prompt employers to explore CHOICE Arrangements:
- The organization wishes to provide health benefits for the first time and cannot support a traditional group plan.
- Anticipated increases in group-plan costs are creating unpredictability in future expenses.
- Employees operate across multiple states or insurance markets.
- Current group plans fail to address the diverse needs of the workforce.
- Issues with participation are making existing strategies unsustainable.
- The employer seeks more control over healthcare contributions while ensuring employee choice remains intact.
These indicators are not definitive but rather part of a broader evaluation process. Key variables such as market availability, employee premium costs, workforce composition, and overall benefit objectives must be factored into this decision-making.
The Importance of Experience in CHOICE
The appeal of CHOICE Arrangements lies in their premise: employers define contributions, while employees select from individual coverage options. However, the execution of this model requires careful planning and management.
Employers need to make decisions related to the plan design, communicate the benefits to employees, confirm eligibility for coverage, manage reimbursements and document compliance, and assist employees who may be unfamiliar with selecting individual insurance. CMS has identified third-party administrators as a useful resource for managing these responsibilities. Such administrators can assist in onboarding, enrollment verification, reimbursements, compliance, and employee communications.
The Role of Third-party Administrators
Working with benefits consultants and third-party administrators can help employers navigate the complexities that accompany shifting from traditional group coverage to CHOICE Arrangements. The goal transcends merely offering various plans; it focuses on the effective design and management of benefits, enabling employers to maintain oversight while empowering employees to utilize their contributions for actual coverage.
Looking Ahead
This increased focus from CMS and SBA will likely encourage more employers and consultants to engage in conversations about CHOICE. However, it also raises several practical questions that need attention:
- Is the employer still considered as providing the benefit?
- Which employees are eligible for participation?
- What is the appropriate contribution amount from employers?
- What types of coverage qualify under this model?
- How are premiums managed and reimbursed?
- What responsibilities falls on third-party administrators?
- How can employers determine whether CHOICE is a better fit than their existing group plan?
The success of implementing CHOICE Arrangements will hinge on finding specific answers to these questions and effectively managing the transition process.
Exploring CHOICE for Future Plans
If your organization is considering whether a CHOICE Arrangement could be beneficial, now is the time to assess its potential fit.


