Bundling home, auto, and motorcycle insurance in Ontario can yield significant advantages, including potential discounts, simplified management, and tailored coverage.
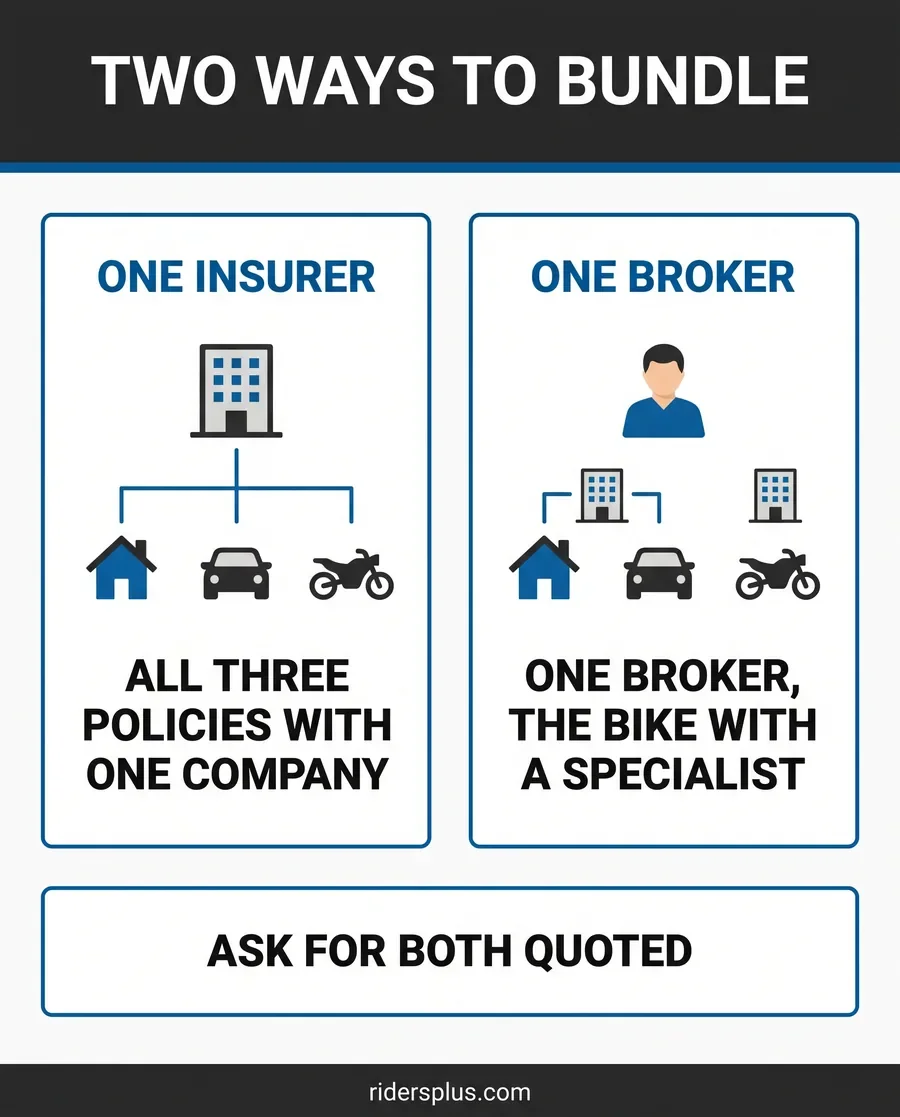
Bundling home, auto, and motorcycle insurance in Ontario means consolidating multiple policies under a single insurer or broker, leading to convenience, a cohesive understanding of your coverage, and potentially lower premiums. While many may wonder what specific benefits bundling brings, it's essential to explore the two prevalent approaches and how they can shape your insurance experience.
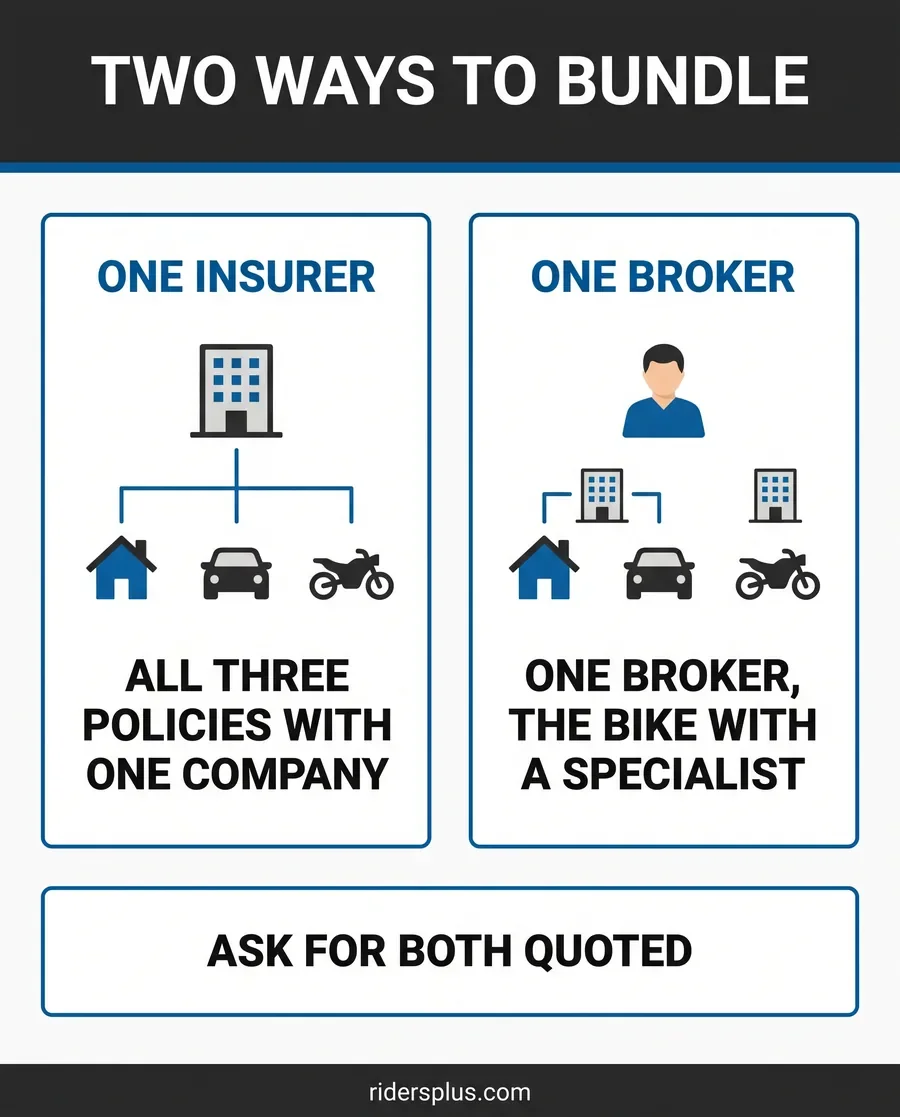
Two Approaches to Bundling Policies
Single Insurer Approach
One common strategy for bundling insurance is to use a single insurance company for all policies—your home, auto, and motorcycle. This method typically allows for easy renewal conversations and often means a consistent multi-policy discount applied across all three policies. However, it’s worth considering that not every insurance company offers motorcycle coverage, which may limit your options. In fact, the Financial Services Regulatory Authority (FSRA) emphasizes that motorcycle insurance is categorized as a specialty product.
Broker with Multiple Insurers
Alternatively, many riders find it more beneficial to engage a broker who can access multiple insurance providers. In this situation, your home and auto policies might be with one insurance company, while your motorcycle is insured by a firm that specializes in motorcycle coverage. This approach allows you to make informed choices for each policy and brings the advantage of having a single broker overseeing all your coverage, which can help identify overlaps or gaps in your insurance plan.
Comparing the Two Approaches: Insurer vs. Broker
| Aspect | Single Insurer | Broker with Multiple Insurers |
|---|---|---|
| Point of Contact | Single broker, single insurer | Single broker, multiple insurers |
| Multi-Policy Discounts | Often available across all policies | Depends on individual insurer policies |
| Choice of Motorcycle Insurer | Limited to those that cover motorcycles | Flexible; best fit for your bike |
| Renewal Synchronization | Easier to align | May differ; broker manages tracking |
| Claims Process | Unified process | Dependent on individual policy holders |
| Best Suited For | Households with compatible home, auto, and motorcycle coverage | Riders needing specialist knowledge or coverage |
The second scenario isn’t simply a fallback; it often provides a better outcome since it allows riders to be matched with specialists who understand the nuances of motorcycle coverage, ultimately ensuring better service.
Factors Influencing the Price When Bundling
While bundling can potentially lead to discounts, there are several factors that can influence the price beyond simple bundling strategies. Here’s what can affect your rates:
- Type of Policies Combined: The traditional combination is home and auto. Adding motorcycle coverage may not always yield additional discounts, particularly if the insurer for the motorcycle differs.
- Motorcycle Specifications: The type and value of the motorcycle, any modifications it may have, and how it’s stored can significantly impact the premium specific to that bike, irrespective of other bundled policies.
- Rider and Household Characteristics: Factors such as experience, claims history, and residential area can affect premiums for motorcycle insurance, just as they do for home and auto coverage.
- Coverage Options: Choices regarding liability limits, deductibles, and additional endorsements can affect the cost of your policies. Having a broker assess these together can help maintain consistent choices.
In essence, while bundling your insurance may simplify payments and potentially reduce costs, it’s not a guarantee of lower premiums. Thus, it’s worthwhile to get quotes in both configurations to determine where financial benefits might lie.
Choosing the Right Setup for Your Household
- Homeowner with One Vehicle and One Motorcycle: This scenario often leads to straightforward bundling. Request quotes from both a single insurer and a multi-insurer broker to find the best deal.
- Household with Multiple Riders: In this case, prioritize the motorcycle coverage first, as it plays a significant role in determining overall costs and coverage needs.
- Renters: Tenant insurance paired with auto and motorcycle policies can also be bundled effectively through a broker, albeit the discount may vary.
- Custom Builds or Unique Bikes: A specialist might be necessary for custom motorcycles, making the broker multi-insurer set-up the more practical option.
Addressing Common Edge Cases
There are a few edge cases that frequently arise when considering insurance bundling:
- Recreational Vehicles (RVs): Adding an RV to your coverage is often possible within the same brokerage, and in some cases, it might even be covered by the same insurer.
- Second Motorcycle: Insuring a second motorcycle is usually more straightforward, as providers often take into account prior relationships and experiences with the rider once they’re established.
- Teen Drivers: Adding a teenager to auto policies generally complicates the calculations and coverage needs significantly, making it essential to have a broker who can manage that complexity effectively.
Final Thoughts on Bundling Insurance
Ultimately, bundling your home, auto, and motorcycle insurance in Ontario offers a way to centralize your coverage management while potentially accessing discounts. The advantages differ based on whether you select a single insurer or utilize a broker who networks with various insurance companies. To ensure you get the most advantageous arrangement, it’s strongly recommended to obtain quotes thoroughly compared both ways. Policyholders in areas like Richmond Hill and York Region or Milton and Halton can start by requesting a motorcycle insurance quote to explore their options effectively.
It’s vital to remember that this article serves as general information and should not be seen as definitive financial, insurance, or legal advice. For personalized advice, consulting a licensed insurance broker is essential.
For further insight, consider downloading our Bundle Questions Checklist to ensure all aspects of your coverage are addressed when considering a bundled insurance strategy.
Frequently Asked Questions
Do I need to bundle with the same company to receive a discount?
No, discounts are often provider-specific. A bundled discount can apply even when separate insurers are utilized; a broker can identify which insurer offers the best overall deal.
Will bundling reduce my motorcycle insurance costs?
Bundling may provide savings, but that depends on various factors. It’s important to analyze detailed quotes to recognize how discounts are applied across different policies.
What happens if I later switch my motorcycle coverage?
Generally, only the motorcycle policy will change, which may alter relevant discounts. Your broker can assist with updating your files seamlessly.
Can renters bundle insurance similarly to homeowners?
Yes, renters can also bundle their insurance for motorcycles and cars, although the available discounts may differ from homeowner arrangements. It’s critical to clarify your rental status with your broker to obtain accurate quotes.


