A New York ruling reinforces that earth movement exclusions can deny coverage for damage from nearby construction, highlighting the critical wording in policies.
In densely populated urban environments, construction projects often lead to disputes with neighboring property owners, and recent legal developments illustrate how insurers may sidestep claims due to specific policy exclusions. A noteworthy decision, Gogam v. Admiral Indemnity Co., underscores the implications of earth movement exclusions and their broad application in property insurance claims.
The Case Overview
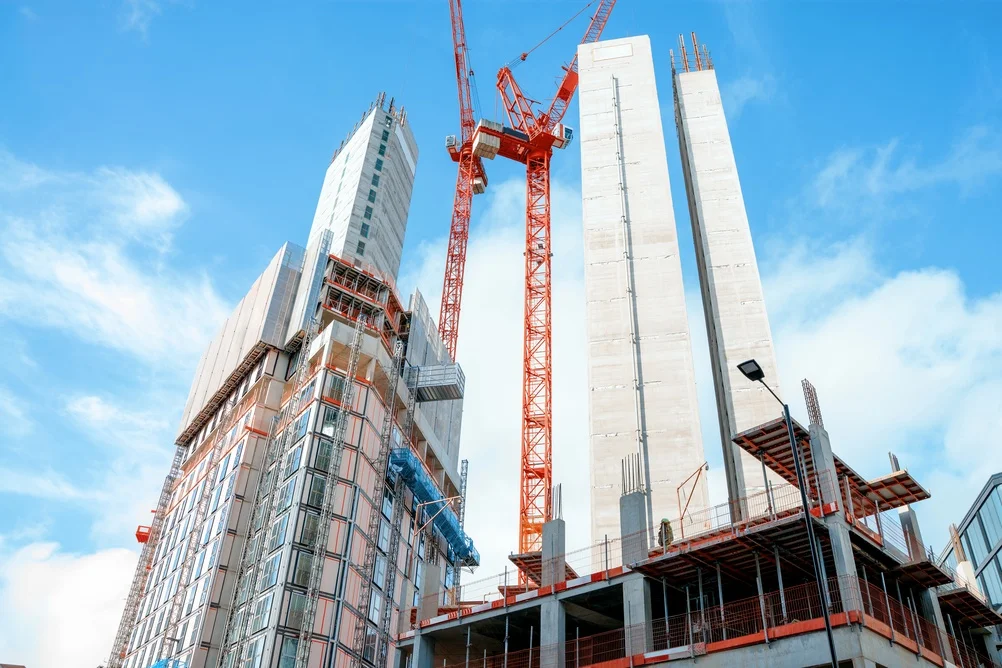
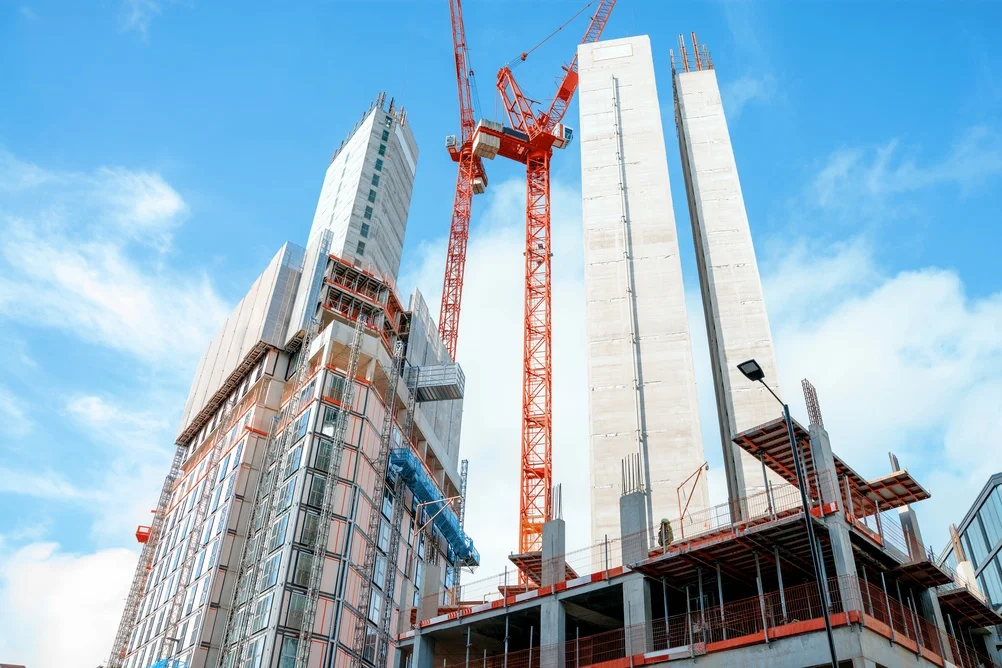
In this case, the insured, owner of a commercial property, experienced significant structural damage attributed to extensive renovations at an adjacent building. The construction, which began in 2020, included major alterations such as gutting the interior, adding two additional stories, and lowering the basement beneath the water table. Before work commenced, engineers had alerted the neighbors about potential negative effects on the insured property, including risks associated with dewatering and underpinning activities. Following the start of the renovations, the insured reported internal and external cracks and even a partial ceiling collapse.
Insurance Coverage Denial
The insurer swiftly denied coverage, citing the policy’s earth movement exclusion. This exclusion states that the insurer “will not pay for loss or damage caused directly or indirectly by” earth movement. It specifically mentions events such as “earth sinking, rising, or shifting,” encompassing conditions that result in settling or structural issues irrespective of whether these events are natural or man-made. The exclusion's language is crucial, as it explicitly includes the phrase “regardless of whether any of the above … are naturally occurring or due to man-made or other artificial causes,” effectively narrowing the coverage scope for the insured.
The Court's Reasoning
The court sided with the insurer, dismissing the insured’s claim based on the straightforward terms of the exclusion. Both parties involved had experts who attributed the damages to a mix of factors including vibration and excavation from the adjacent construction. The court determined that the cause of the damage clearly fell within the definition of earth movement, thereby confirming the exclusion's applicability. As articulated by the insurer’s expert, any contributing factor related to the construction work infringing on the insured’s property was sufficient to uphold the exclusion.
This ruling aligns with established legal precedents in New York regarding earth movement exclusions, particularly referencing Bentoria Holdings, Inc. v. Travelers Indemnity Co., where similar exclusionary language was upheld to deny claims arising from excavation activities. The Gogam case reinforced prior decisions by emphasizing that whether damage stems from vibrations or direct excavation activities, the exclusion effectively precludes coverage if it results from earth movement.
Implications for Policyholders and Insurers
What does this mean for property owners and insurance practices? For policyholders, the decision serves as a critical reminder of the significance of thorough policy reviews before initiating construction or renovations. Potential risk factors and applicable exclusions should be clearly understood to avoid unexpected denials during claims processes. It's advisable for property owners in similar urban environments to consult with professionals prior to large construction projects to evaluate the potential effects on surrounding properties and their coverage.
From an insurer’s perspective, Gogam highlights the necessity of clear wording in policy exclusions. Insurers must ensure their policies explicitly capture both man-made and natural causes of earth movement to preclude coverage effectively. The ruling, which upheld the exclusion despite prior payments made to the insured, also emphasizes the importance of clear communication and documentation during the claim investigation. A well-articulated reservation of rights can protect insurers from inadvertently admitting liability for claims that may later be found outside coverage bounds.
Conclusion
Ultimately, the Gogam decision confirms that carefully crafted earth movement exclusions, particularly those that pertain to man-made activities leading to ground displacement, remain a robust defense for first-party property insurers in New York. It illustrates the balance between assuring coverage for legitimate claims while safeguarding against the broad risks posed by adjacent construction activities. Property owners should actively engage with their insurers and legal advisors to navigate potential pitfalls in coverage, especially in bustling urban settings where construction is frequent.


