A cross-state move can change your insurance options, Medicaid eligibility and the care you can legally access. Here's what to check before you pack the truck.
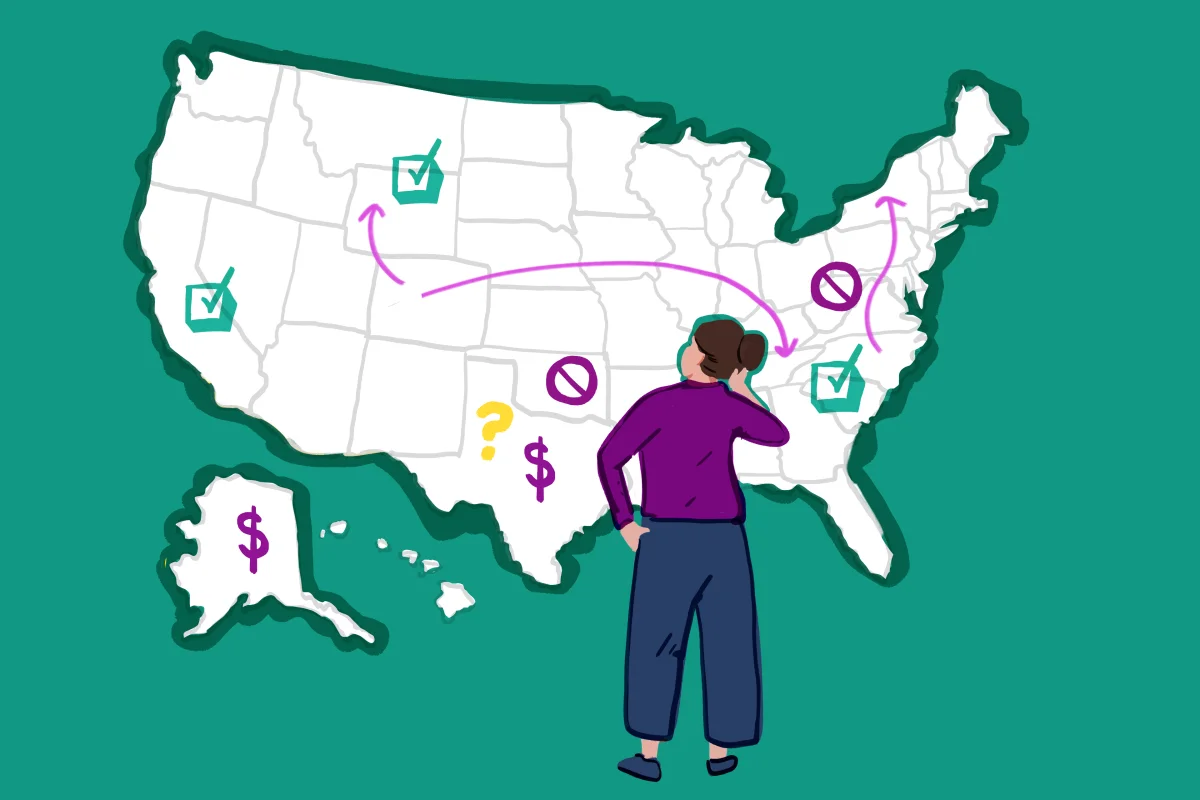
A new job and a first apartment get most of the attention when people move across state lines. Health coverage tends to come up later, often after the first appointment in the new place turns into a problem. Moving can change your insurance options, your eligibility for public coverage and even which treatments and providers are available to you. Checking those things before the move is far easier than sorting them out afterward.
Jael Samano found that out the hard way, or at least the early way. She moved from Illinois to Wisconsin after college, starting an environmental consulting job and living alone for the first time. The move was expected. What caught her off guard was realizing, while still seeing her therapist before the move, that she'd need new providers and would have to learn a new health insurance system through her employer. "I feel so adult-y saying it, but it's definitely at the top of my list right now," she said.
Start with your insurance options
If your coverage comes through a job or school, you may not need to do much right away. If it doesn't, the picture changes. You can shop for a plan on healthcare.gov to see what's available in your new state. Moving counts as a qualifying life event under the Affordable Care Act, which means you can enroll in a new plan outside the usual open enrollment window. That's a useful detail, but it doesn't make the decision simpler. Plans differ by state in price, insurers and networks, so comparing the actual doctors and hospitals you'd use matters as much as the monthly premium.
Medicaid deserves a closer look, because eligibility is set state by state. Medicaid is publicly funded coverage for people with lower incomes or disabilities, and it can be a real lifeline during a transition. In 40 states and Washington, D.C., it covers unmarried people earning up to $22,000 a year. In states that haven't expanded Medicaid under the Affordable Care Act, including Texas, Tennessee and Florida, it's extremely hard for a single adult without children to qualify. KFF's Medicaid fact sheets break down the rules by state, and they're worth reading before you choose a destination if Medicaid might be part of your plan.
Jennifer Tolbert, deputy director of the Program on Medicaid and the Uninsured at KFF, put the stakes plainly. "If you need Medicaid as a source of coverage, you should not move to states that have not adopted the Affordable Care Act's Medicaid expansion," she said.
There's also a timing wrinkle. Work requirements for Medicaid take effect in most states in 2027, which means many enrollees will have more paperwork to keep their coverage. If you're planning a move that lands you in Medicaid during that period, it helps to know what documentation you'll need to stay enrolled and to set reminders for renewal dates.
Staying on a parent's plan
Young adults often assume a move means losing a parent's health insurance. Usually it doesn't. If you're on a parent's plan, you can generally keep that coverage until the end of the calendar year in which you turn 26, regardless of where you live. The catch is network. A parent's plan may have a narrow set of providers in your new area, and those doctors may be far from where you now live and work.
A few states go further. Florida, for example, allows some young adults to remain on a parent's plan until age 30 if they meet certain criteria, though they must stay a Florida resident or be a student. Several states also extend coverage past 26 for people with disabilities. Those rules are specific, so check the details for the state you're moving to and the plan your parents hold, rather than assuming the extension applies to you.
What care you can legally access
Insurance isn't the only thing that shifts. The treatments you can legally access also vary by state, and that's easy to overlook when you're focused on premiums and networks.
Marijuana rules are a good example. According to the National Conference of State Legislatures, 40 states allow residents to buy marijuana for medicinal purposes, and about two dozen allow recreational use. Most other states permit CBD products, though Idaho and Kansas have banned marijuana in all forms. If you rely on a medical cannabis prescription, the new state's rules determine whether you can keep that treatment in place after the move.
Abortion access is another area where the rules change sharply at the state line. According to KFF, 13 states have banned abortion altogether, and six others have cutoffs in the first trimester. Restrictions affect more than abortion itself. Reporting from ProPublica has documented cases in which restrictions kept some women from getting timely medical help with miscarriages. Even if you don't expect to need abortion care, it's worth understanding how the state's laws could affect other reproductive health care.
Alina Salganicoff, director of the Women's Health Policy Program at KFF, made the timing point. "If you're moving to a new state and you're considering making this kind of change, it's important to research and know what your options are before you get there, not once you get there and you can't make changes," she said.
Telehealth and out-of-state providers
Your current therapist or doctor may be able to keep seeing you after the move, but that depends on licensing. Some states recognize providers licensed elsewhere, usually through multistate licensure compacts or telehealth registries. In many cases, though, a provider must be licensed in the state where the patient is located. That's a meaningful limit if you've built a relationship with a specialist you don't want to leave.
Ask your providers before you move whether they can continue care remotely, and under what conditions. Get the answer in writing if you can, and ask whether there's a transition plan for patients who can no longer be seen. Then compare that with what's available near your new home, since you may need a local provider sooner than you'd like.
A practical order of operations
Here's the sequence I'd follow. Before the move, check whether your current coverage ends and when. Next, look up Medicaid eligibility and marketplace plans for the new state, and compare the provider networks, not just the prices. Confirm which of your current doctors and prescriptions will carry over. Then review the state's rules on any treatments you depend on. If you're on a parent's plan, confirm the network in your new area before you rely on it.
Nothing here guarantees that a particular plan or program will fit your situation, and eligibility rules change. The useful move is to treat your health coverage as part of the relocation checklist, alongside the lease and the movers. Most of the surprises people run into after a cross-state move could have been caught with a few weeks of research before the boxes went on the truck.